Renovating a whole house over three years works when you treat the three years as a payment schedule instead of a construction schedule. Each phase gets sized to a funding event your household can actually meet, every job that opens the same wall or the same floor gets bundled into one contract, anything that protects the structure gets funded before anything that decorates it, and every phase ends at a point where the house is still livable and weather-tight. Get those four in order and the deadline stops mattering.
I keep the plan on the side of the refrigerator, folded into three columns. Left column: what the house needs. Middle: where the money actually comes from, which for us is not a product but a rhythm. The bonus that lands in spring. The car payment that ends in October. The two months a year with a third paycheck. Right column: the stopping point, written as a physical condition instead of a date. One full bath working. Kitchen sink hooked to the drain. Attic hatch closed. No holes in a ceiling anywhere.
When all three columns agree, the phase starts. When they don't, it waits, and I don't feel bad about it.
I learned that sheet the hard way. Eleven days one spring, the kitchen sink was disconnected, the dishwasher sat in the hallway, and a new countertop leaned against the garage wall on two sawhorses. We washed dishes in the bathtub. The money was fine. The contractor was fine. What broke was a phase that ended in the wrong place. Almost finished with a kitchen is not almost finished. It's no kitchen.
Now I build the schedule backwards from the phases, and the phases backwards from the money.
Three years is a payment schedule wearing a tool belt
A phase should map to one funding event, or at the outside, two. If a phase needs three bonus cycles to finish, it isn't a phase. It's a wish, and it will be under construction the entire time, which is its own kind of burnout.
So the first question I ask isn't what's next on the house. It's when money arrives, and how much of it can go to the house without touching what we live on. The answer changes the order of work more often than the condition of the house does. A kitchen with a blown-out cabinet box can survive another eighteen months if the roof has a soft spot. The roof can't.
There's a version of this that looks like a spreadsheet and a version that looks like a calendar, and the spreadsheet wins every time. Two funding events a year is a comfortable pace for a whole-house project. Three is aggressive. Four means you're probably pulling from the next phase, which is how three-year projects turn into five-year projects.
The bundling rule: same cavity, same contract
Walk the house with a pencil and mark every place where somebody will have to open something up. Then group the marks by hole.
Anything that requires the same hole belongs in the same contract, and that's a budget decision as much as a scheduling one. When you phase work across years, you pay for the setup two or three times: the dumpster delivery and pickup, the dust walls and floor protection, the crew's mobilization day, the permit and the inspection, the punch-list trip at the end, the drywall patch and repaint where they opened the wall. As a rule of thumb I figure repeated setup at somewhere in the range of 10 to 15 percent of a phase's value, and that's before counting anything that has to be undone. You don't get a receipt for that money. It just disappears.
Bundles that are almost always worth it
An electrical service upgrade with any circuit you already know you want. A range hood, a bathroom fan, a heat pump, a dedicated outlet in the garage. The panel is open, the permit is pulled, the inspection is scheduled. Adding that circuit two years later means all of it again, plus a hole in a finished wall.
A bathroom tear-out with the plumbing stack behind it, the laundry connections beside it, and the hall closet that shares the same chase. One plumber, one inspection, one set of holes.
A roof with gutters, downspout drainage, chimney flashing, and attic ventilation. One scaffold, one crew, one stretch of noise, and no second trip for the thing you forgot.
Siding, windows, and exterior paint, if the siding is coming off anyway. The sheathing is exposed exactly once.
Bundles that are not worth forcing
The guest bedroom at the end of the hall shares one thing with the bathroom project: hallway paint. Paint it when you get to the hallway and leave the room alone.
Same for a formal dining room, a finished basement, a third bathroom nobody uses. The value of bundling is avoiding a hole reopened. If nothing has to be opened, there's nothing to bundle.
Here's the tradeoff, and it's real: bundling demands a lump of money in a single window. If the lump isn't there, you phase it and you pay the premium, and the honest move is to say that out loud when you write the plan instead of being surprised by it later. Stretching work across years costs more in total. Sometimes that's the only version your household can afford. That's a legitimate answer, not a failure.
Protect-the-house money goes first, always
Roof. Water intrusion. Grading and drainage that sends water at the foundation. A supply line that's weeping. A sewer line that backs up. Whatever the house's version of this can destroy everything else is, it gets funded before the first cosmetic dollar moves. Not because it's more fun, but because new drywall under a slow leak becomes new drywall again within a year, and the second time you're paying for demo too.
I run it as one question: can this thing destroy something I just paid for? If yes, it goes first, in this phase or an earlier one.
This is the part people skip when they're excited. It's also the part that makes a three-year plan hold together, because the house stops generating new emergencies while you're saving for the next phase.
Which rooms earn the early slot
Kitchens and bathrooms. Highest daily use, the biggest share of the household's friction, and the two rooms people actually look at when a house changes hands. A kitchen that works changes how every day goes. A guest room with bad carpet changes nothing except the door you keep closed.
If I had to sketch a hypothetical split for a house that needs everything, it would look roughly like this, as percentages of the total project: around 40 percent to the envelope and the mechanical systems, around 30 percent to the kitchen, around 20 percent to the bathrooms, and the remaining slice to everything cosmetic. Treat that as a shape, not a quote. When I found cloth-wrapped wiring in the second house, the shape moved and cosmetics went to the bottom of the list for two years.
What can wait: guest rooms, formal dining, a second living area, the front-yard landscaping, the front door, and the light fixtures you keep almost buying. Waiting on those costs you nothing but wanting them.
Contingency is a percentage, not a line item
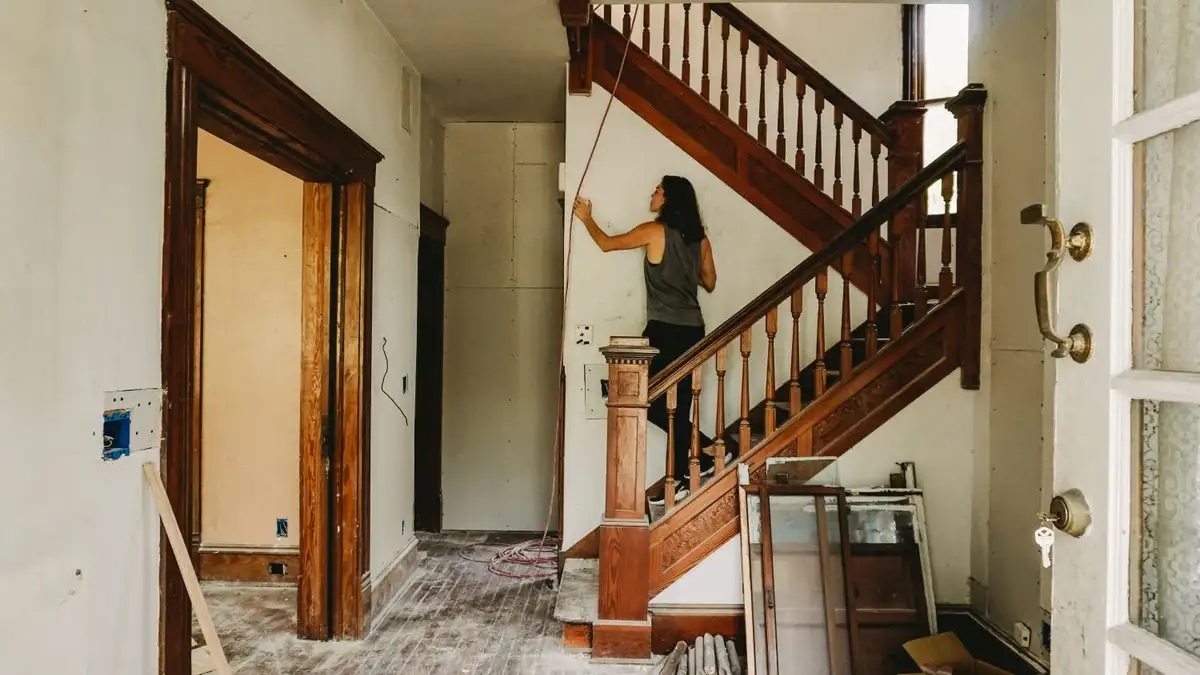
Somewhere between 15 and 20 percent of each phase's value sits inside that phase as contingency, and it does not get spent on nicer tile. It exists because tile comes off a wall and there's rot behind it, because the floor around a toilet is soft, because a wall that should have insulation has newspaper in it. In older housing stock you will meet all three.
The rule that keeps this honest: if contingency is gone before the phase is roughly 60 percent complete, the phase stops at the next stopping point, whatever that looks like, and the rest waits for the next funding event. Contingency isn't pessimism. It's the price of not knowing, and you never know.
One more version of the same rule: upgrades are not contingency. If you decide mid-phase that you want a different countertop, that money comes out of the next phase's budget, not out of the surprises bucket. Mixing those two is how a phase runs out of money with the walls still open.
Every phase ends where the house still works
This is the piece that makes the rest survivable. Before a phase starts, write the stopping point down as a condition, and hold the contractor to it.
A working stopping point looks like this: one full bathroom functional, hot water on, heat on, laundry usable, the envelope closed with no open holes, no energized wiring hanging out of a wall, and a sleeping area separated from the dust. If a phase can end there, pausing is a decision. If it can't, pausing is an emergency and you'll pay whatever it takes to get out of it.
Concretely, in a kitchen: cabinets set, countertop on, sink and dishwasher connected, range in and working, backsplash missing, a couple of outlet covers missing. That's a legitimate stopping point. Sink disconnected and countertop in the garage is not.
That eleven-day stretch washing dishes in the bathtub taught me more about budget planning than any spreadsheet. The burnout wasn't the money. It was two months of living in the wrong stopping point.
The forty minutes a month that keeps the whole thing honest
Once a month I sit down with the sheet for about forty minutes. No contractors, no showroom, no decisions. I mark what the phase has actually spent against what I thought it would, check whether the next funding event still exists, and look at the next stopping point to see whether it's still something I could live with in December.
Three things have to be true before a phase starts: the scope is written down, that phase's contingency is funded and sitting in its own bucket, and the stopping point is defined. If any of the three is missing, we wait. Waiting has never once cost me as much as starting early did.
Where this framework breaks
If there's an active leak, three years is the wrong number. Compress it. Fix the water, then stop and save.
If the systems in an old house are tangled together, plumbing and electrical and framing all sharing the same two walls, the honest bundle may be the whole downstairs at once. That's a save-longer-and-do-it-once plan, not a phase plan, and pretending otherwise means reopening the same wall three times.
If your household can't live in a construction zone for three years, phasing around a short-term place to stay during the kitchen is a legitimate alternative, but it's a different budget with its own line items, and it changes the arithmetic.
And if the money rhythm changes, a job, a move, a new baby, a medical year, you rebuild the schedule at the next ledger night. The plan was never the point. The three columns are the point.
Mine is still taped to the side of the refrigerator. It's on its second sheet now, the first one having gone soft at the fold lines. The dumpster from the first phase is long gone, the zipper door from the kitchen finally came down, and most of the third column is checkmarks. Three years isn't long when you know what each year is buying.